The 19th-century geologist Charles Lyell popularized the concept of “uniformitarianism,” a long word that reflects the simple idea that the natural forces shaping the earth today are the same ones that have consistently shaped it throughout history. A similar principle applies to commodities we extract from the ground, like oil and copper. While events like wars, tariffs, and AI are impacting commodity prices right now, supply and demand ultimately drive these markets in the long run.
As an asset class, commodities have not only outperformed this year, but have also supported other areas of the market such as U.S. stocks. Commodities are closely watched because they are also sensitive to economic conditions. Oil prices have swung from month to month, copper has climbed to new record highs, and precious metals surged to all-time highs at the start of the year before pulling back. Short-term price swings in the commodity market are not unusual, and the forces behind them, including geopolitics, tariffs, and changing economic trends, are difficult to predict.
The important question for investors is not where oil or copper will trade next week, but what supply and demand tell us about the broader economy, long-run trends, and how they interact with a well-constructed portfolio. Commodities can signal global conditions, and their volatility is a natural part of how they work. How can investors stay grounded when commodity markets move sharply?
Oil prices remain tied to geopolitical uncertainty
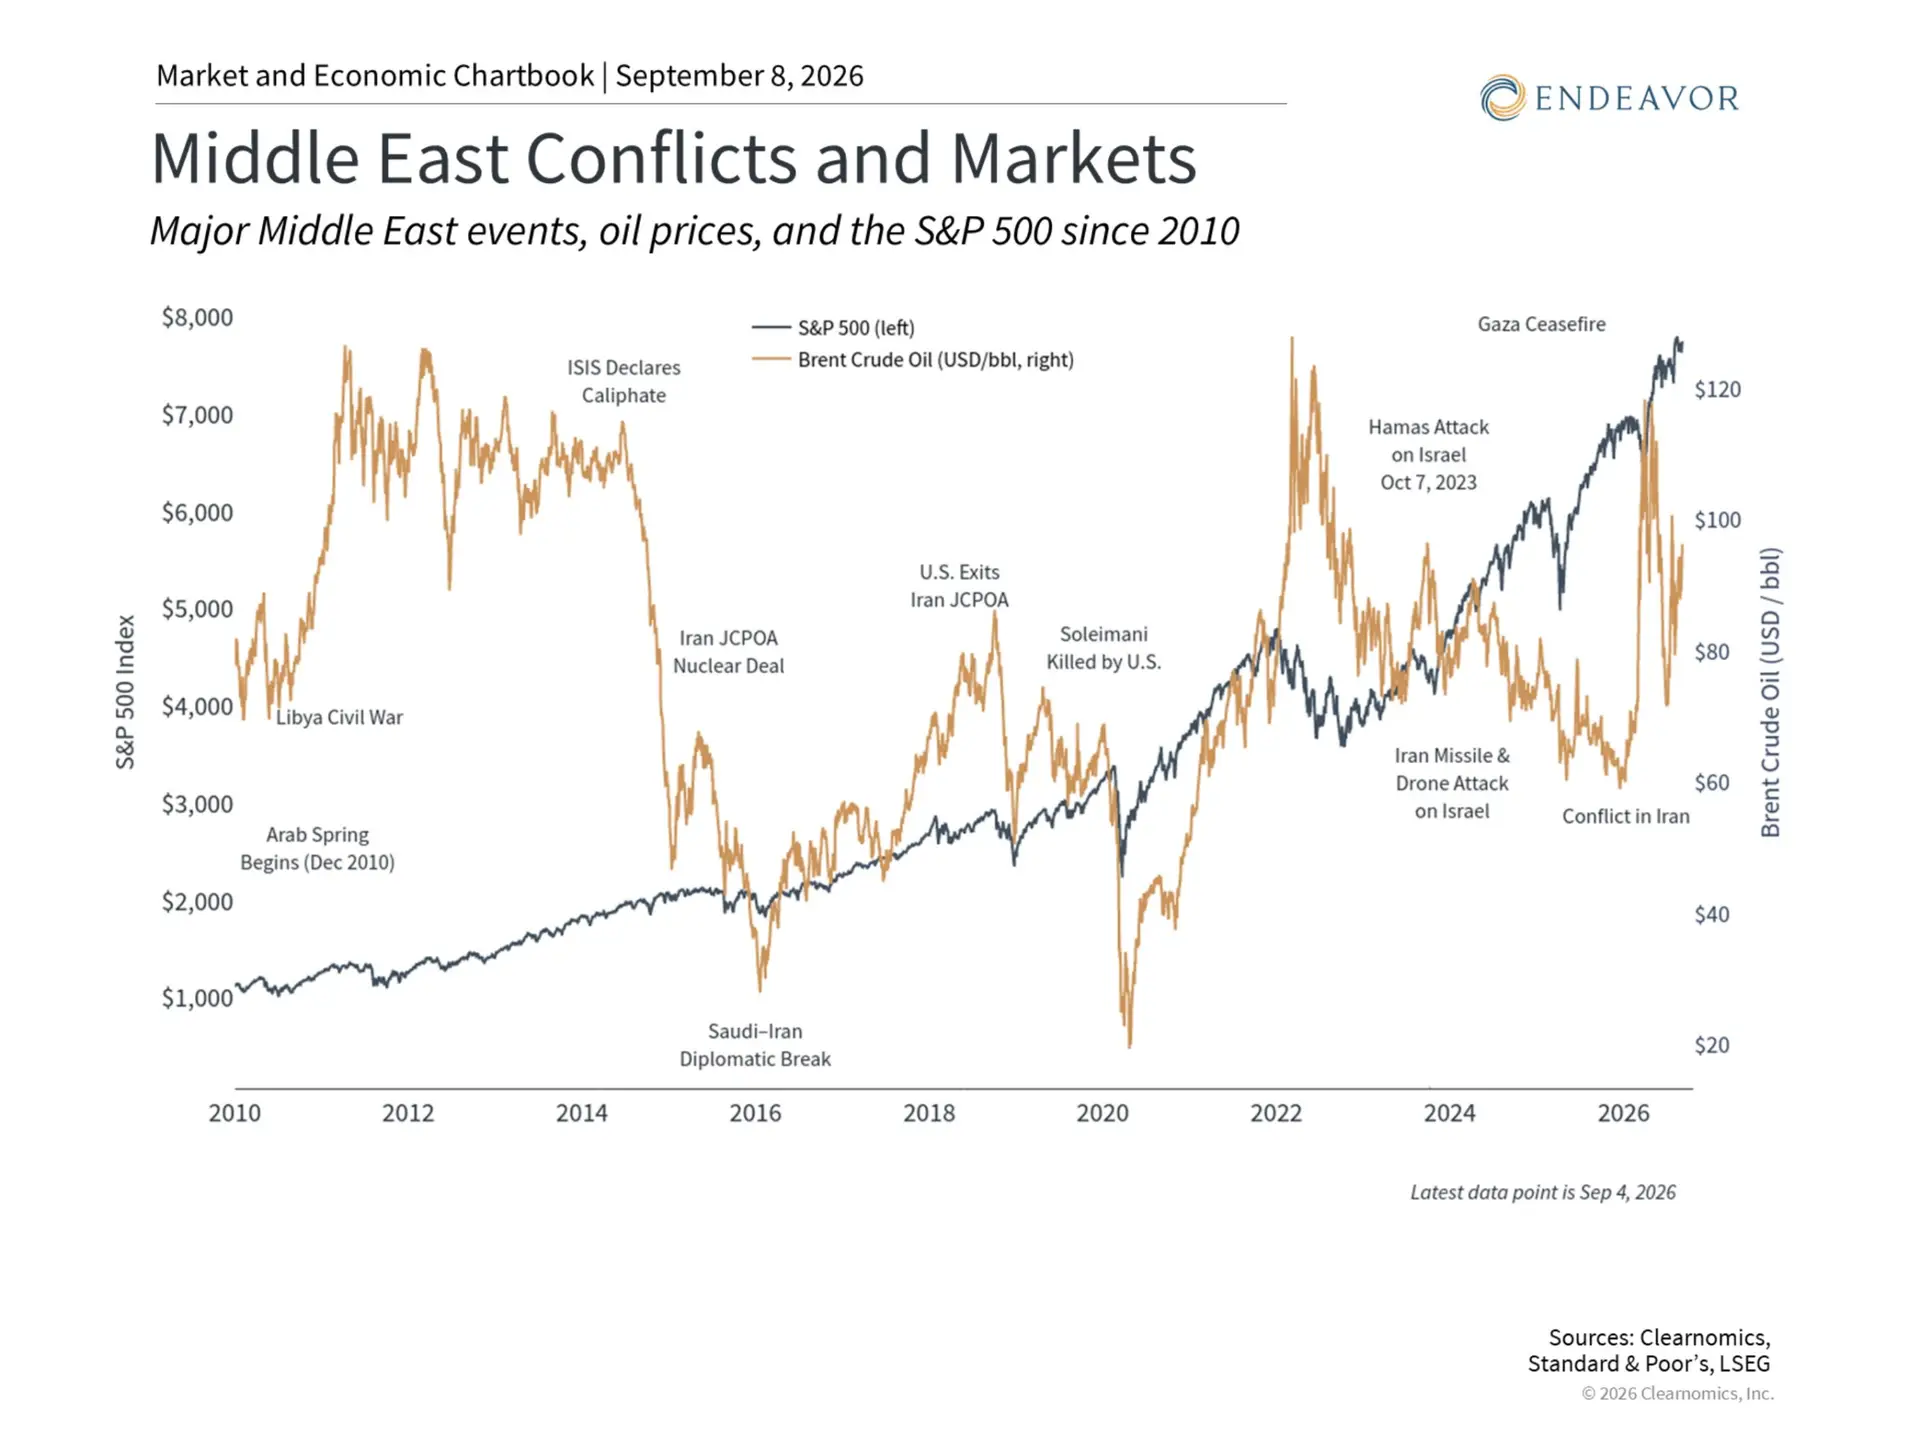
Oil markets have fluctuated dramatically this year, showing how sensitive they can be to global events and how difficult commodity prices are to forecast. Oil jumped to multi-year highs back in March when the war in Iran began. Since then, Brent crude has oscillated from as low as $72 per barrel at the start of July back toward $100 as of today, touching a seven-week high.
The primary driver of these swings is the ongoing conflict in the Middle East, which has continued despite multiple ceasefire attempts and failed peace negotiations. Most recently, the Houthis, a group of militants in Yemen, conducted strikes on Saudi Arabian energy infrastructure, raising new concerns about regional supply disruptions and pushing Brent crude back toward $100 per barrel.
While the Strait of Hormuz, which connects the Persian Gulf to the rest of the world, is still the main focus in energy markets, Houthi forces have continued to target the Bab al-Mandab Strait, another important transportation chokepoint. Since it sits at the southern entrance to the Red Sea, it is an increasingly vital route for Saudi oil exports. Overall, hostilities across the Middle East have made oil shipping extremely fragile.
For everyday consumers, these moves translate directly into pump prices. The national average for regular-grade gasoline has hovered around $4.15 per gallon according to AAA, and over $5.00 per gallon for premium, levels that have kept energy costs elevated and headline inflation higher than policymakers would prefer.1 This has affected inflation numbers all year since the energy component comprises over 7% of the total Consumer Price Index.2
Historically, oil price volatility of this kind is not unusual. During the Russia-Ukraine conflict in 2022, for instance, Brent crude surpassed $120 per barrel before declining sharply. In the mid-2000s, oil stayed around $100 for several years as global demand grew rapidly ahead of the financial crisis. Today, high oil prices are clearly driven more by geopolitics than by an overheating economy. Additionally, with the U.S. now producing more than 13.8 million barrels per day, it is somewhat more insulated from shocks than in the past.3
Copper reflects both trade policy and long-term structural demand
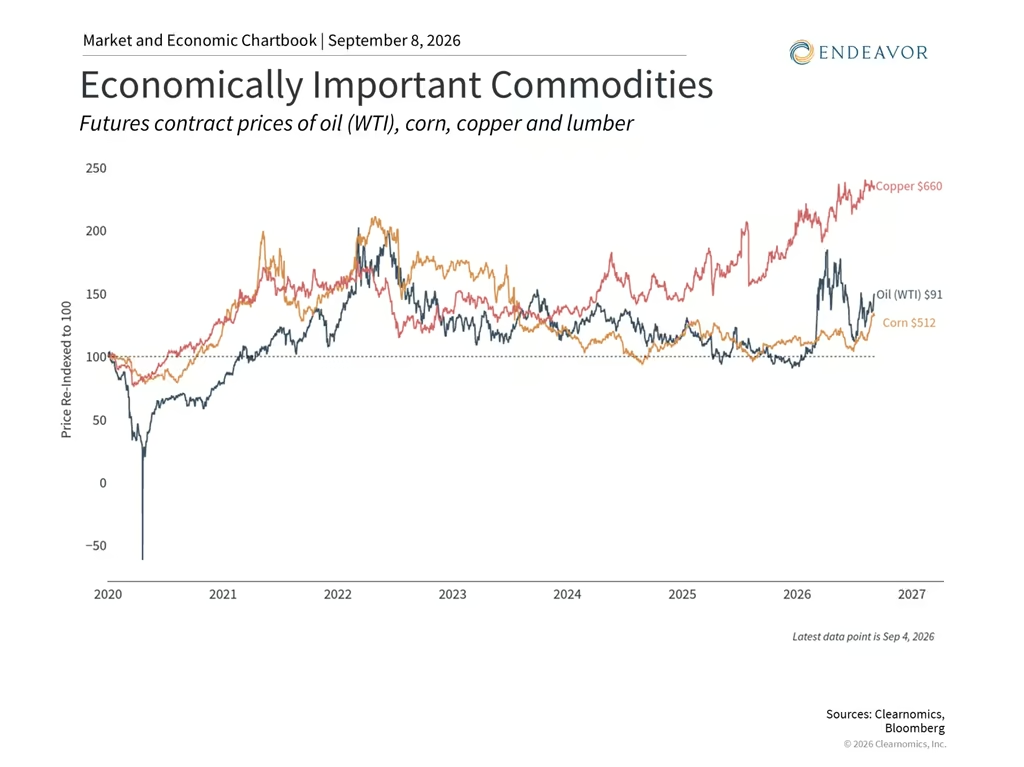
While oil has been the biggest commodity story this year, copper has also hit record highs. Investors often use the term “Dr. Copper” to refer to the metal, since it can be perceived as a forward-looking economic indicator. This is because copper has a wide array of industrial uses, from building construction and energy to electronics and transportation.
The latest jump in copper prices is driven primarily by two factors: tariff concerns amid tight supply and long-term structural demand from trends such as AI data centers. On tariffs, concerns remain about possible new U.S. import duties on refined copper. It may seem unusual that the U.S. would impose additional tariffs on copper given how important it is, but the administration’s goal is exactly to promote domestic production for national security reasons. These tariffs are being explored under Section 232 of the Trade Expansion Act of 1962, which targets foreign reliance on sensitive goods.4 These issues, along with tight supplies and slower production, have driven copper prices higher.
At the same time, demand for copper has jumped. AI data centers, for instance, naturally use thousands of tons of copper.5 Copper is not only a critical component in power delivery systems, including electrical wiring, but it is also highly efficient at transferring heat. This makes it a critical part of the infrastructure needed for keeping large data centers and thousands of semiconductor chips cool. As the “hyperscalers” continue to build larger data centers, demand for copper has continued to rise.
As with most commodities, prices and demand can react quickly, but it takes a long time to bring new production online. This naturally leads to large swings in prices. While copper differs from precious metals, it parallels the large rallies and pullbacks in gold and silver at the beginning of the year. Across all these metals, the key is to maintain a longer-term perspective and avoid overreacting to near-term moves.
Commodities are best viewed in a portfolio context

For long-term investors, what matters is what these commodities signal about the broader economic environment and how these assets behave within a diversified portfolio.
Year-to-date, the Bloomberg Commodity Index is the leading asset class, reflecting high oil prices and the supply and demand dynamics for other metals and materials. The chart above shows how volatile commodities can be, with the asset class outperforming in some years and underperforming in many others.
What matters most is that many other asset classes have performed well this year too. Emerging market stocks, small caps, U.S. stocks, and other major asset classes have also delivered solid returns. This is partly because these parts of the market also benefit from higher commodity prices. The energy sector, for instance, has been the best-performing S&P 500 sector for this reason.
All of this underscores the importance of maintaining a portfolio perspective, rather than focusing on individual asset classes or investments. The purpose of a well-constructed portfolio is to benefit from all of these trends, which can interact in complex ways, while managing risk, all in service of achieving long-term financial goals.
The bottom line? Commodity prices are sensitive to geopolitics, trade policy, and economic cycles. A balanced portfolio that includes exposure to different asset classes remains the best way to navigate these swings to achieve financial success.
Endeavor Advisors, LLC (“Endeavor”) is a registered investment advisor. Advisory services are only offered to clients or prospective clients where Endeavor and its representatives are properly licensed or exempt from licensure.
The views expressed in this commentary are subject to change based on market and other conditions. These documents may contain certain statements that may be deemed forward-looking statements. Please note that any such statements are not guarantees of any future performance, and actual results or developments may differ materially from those projected. Any projections, market outlooks, or estimates are based upon certain assumptions and should not be construed as indicative of actual events that will occur.
The information provided is for educational and informational purposes only and does not constitute investment advice, and it should not be relied on as such. It should not be considered a solicitation to buy or an offer to sell a security. It does not take into account any investor’s particular investment objectives, strategies, tax status, or investment horizon. You should consult your attorney or tax advisor.
Diversification does not ensure a profit or guarantee against loss.
Investing in commodities entails significant risk and is not appropriate for all investors.
- https://gasprices.aaa.com/ ↩︎
- https://www.bls.gov/cpi/tables/relative-importance/home.htm ↩︎
- https://www.eia.gov/dnav/pet/hist/leafhandler.ashx?n=pet&s=mcrfpus2&f=m ↩︎
- https://www.congress.gov/crs-product/IN12614 ↩︎
- https://www.spglobal.com/en/research-insights/special-reports/copper-in-the-age-of-ai ↩︎